Washington drivers shopping for car insurance in 2026 face the same six or seven big names everyone else sees in ads, but not every one of them fits every driver. This ranks the best car insurance companies in Washington by who they actually serve well, not by ad budget.
- State Farm wins overall for Washington drivers who want a local agent and broad coverage in 2026.
- USAA is the strongest pick for military families, but eligibility is restricted to service members and relatives.
- PEMCO is a Pacific Northwest-only mutual insurer built specifically for Washington and Oregon roads.
- GEICO and Progressive fit digital-first shoppers and drivers with a rough driving record.
- Washington law requires minimum liability limits of 25/50/10 no matter which company you pick.
Why this matters
Washington requires every driver to carry liability coverage of at least $25,000 per injured person, $50,000 per accident, and $10,000 for property damage, commonly written as 25/50/10. Drive without it and you risk a suspended license on top of the accident costs.
Comparing company names alone doesn't tell you which one will actually write you a good policy. Eligibility, driving history, and where in Washington you live change the math for every carrier on this list. Working with an independent insurance agent who checks multiple carriers at once saves the twelve-phone-call version of this process.
Rates and underwriting rules also shift year to year, so what won last year's comparison isn't guaranteed to win in 2026. The ranking below is built on how each company is actually structured — who it serves, what it's known for, where it falls short — not on a single number that goes stale in six months.
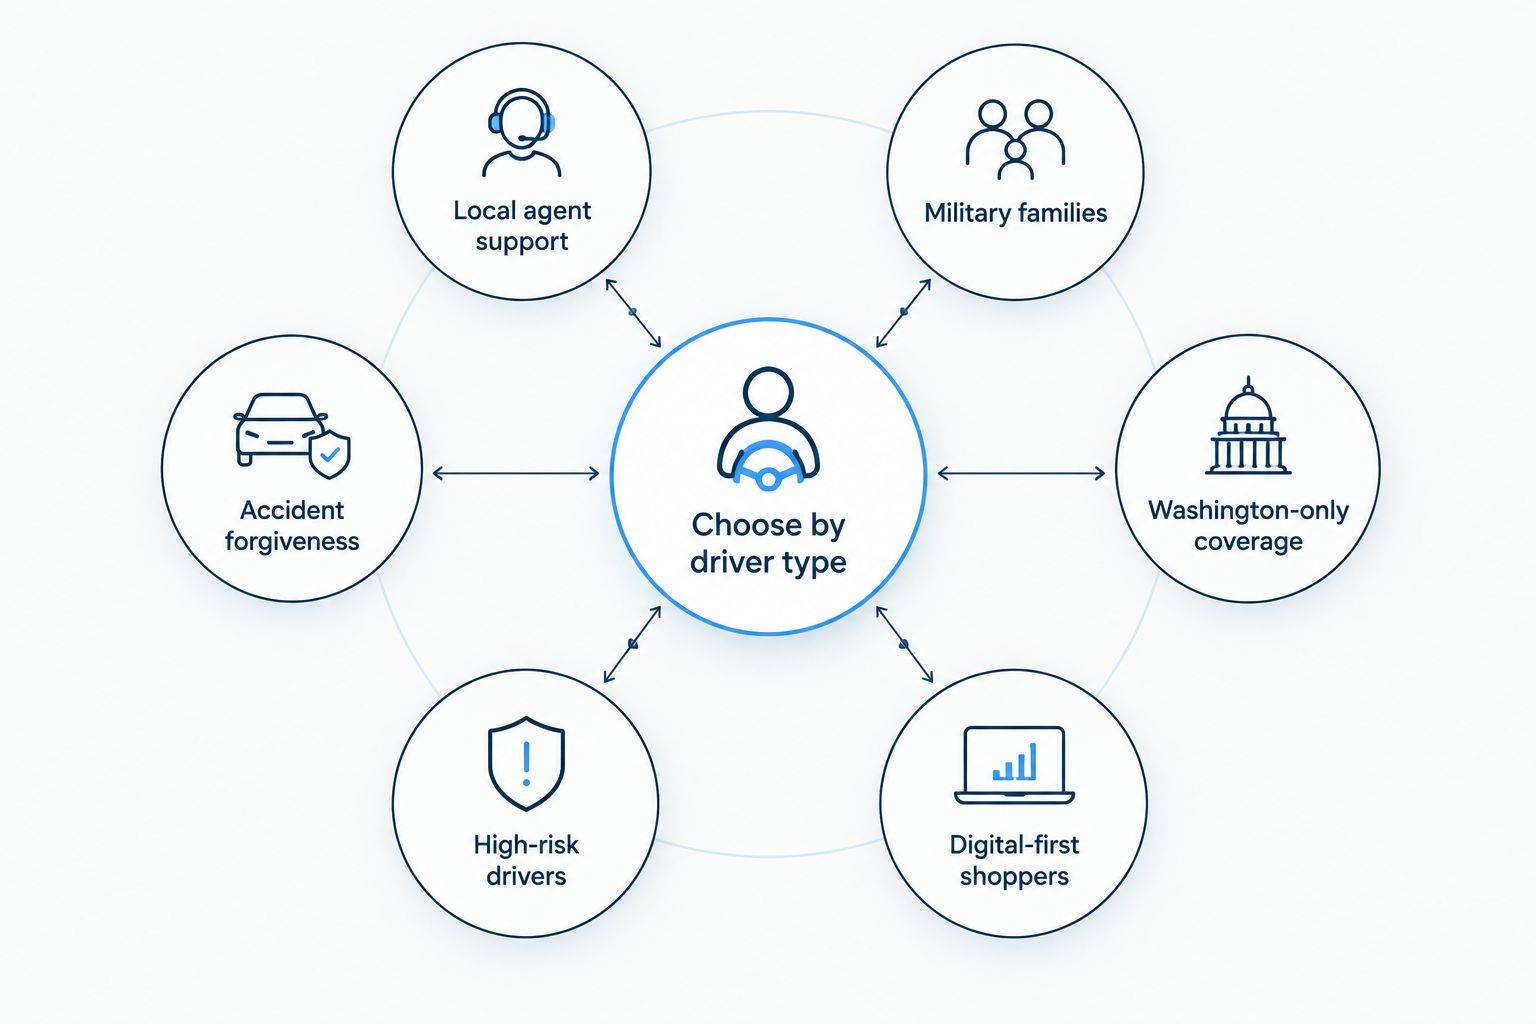
Best overall for Washington drivers: State Farm. Best for military families: USAA. Best for staying Washington-specific: PEMCO. Best for high-risk or non-standard drivers: Progressive. Best for digital-only shoppers: GEICO. Best for accident forgiveness: Allstate.
What makes the best car insurance company in Washington
- Local agent access — someone in-state you can call after a claim, not a national call center
- Coverage built for Pacific Northwest risk — rideshare endorsements, wildfire smoke damage, winter-driving claims history
- Eligibility rules — open to any driver versus restricted to a membership group
- Digital tools versus in-person service — app-only management or a real office
- Telematics or usage-based discount programs — Snapshot, Drivewise, and similar programs that reward driving habits
- Multi-state licensing — matters if you might move out of Washington later
Best car insurance companies in Washington 2026: at a glance
| Company | Best for | Standout feature | Key limitation |
|---|---|---|---|
| State Farm | Local agent support | Large network of local WA agents | Not the cheapest for high-risk drivers |
| USAA | Military families | Military-focused claims process | Membership restricted to military/veterans/family |
| PEMCO | Washington-only coverage | Pacific Northwest mutual insurer, WA/OR focus | No coverage outside Washington and Oregon |
| GEICO | Digital-first shoppers | Fully self-service app | Limited in-person agent support |
| Progressive | High-risk drivers | Snapshot program and Name Your Price Tool | Snapshot pricing shifts with driving behavior |
| Allstate | Accident forgiveness | Drivewise telematics, accident forgiveness feature | Agent availability thins in rural WA counties |
1. State Farm: best car insurance in Washington for local agent support
State Farm runs a wide network of local captive agents across Washington, from Spokane to Tacoma to Seattle, alongside standard auto, home, and life products. In 2026 it remains one of the largest auto insurers in the country by volume, which means broad reinsurance backing and a deep bench of coverage add-ons.
State Farm pros:
- Local agents in most mid-size and large WA cities
- Bundling discounts available when you pair auto with home or renters coverage
- Wide menu of add-on coverage, including rental reimbursement and roadside assistance
State Farm cons:
- Rates for drivers with recent tickets or accidents can run higher than usage-based competitors
- Agent office quality varies — some are single-agent shops, others have full staff
Best for: Washington drivers who want a person to call after a fender-bender, not a chatbot. Verdict: Buy.
2. USAA: best car insurance in Washington for military families
USAA sells auto insurance exclusively to active-duty military, veterans, and their eligible family members, and operates mostly by phone and app rather than storefronts. Its claims process is built around military life — deployments, permanent-change-of-station moves, and base-adjacent driving.
USAA pros:
- Consistently strong reputation among military households for claims handling
- Bundling with other military-focused financial products
- Streamlined digital claims process
USAA cons:
- Not available to Washington drivers outside the military-connected eligibility group
- Very limited physical branch presence in the state
Best for: Active-duty, veteran, or military family households living in Washington. Verdict: Wait — only relevant if you actually qualify for membership.
3. PEMCO: best car insurance in Washington for staying regional
PEMCO is a Seattle-based mutual insurer that sells auto coverage only in Washington and Oregon, built specifically around Pacific Northwest driving conditions like wet roads and mountain-pass commutes. Being member-owned, it doesn't answer to outside shareholders the way national carriers do.
PEMCO pros:
- Claims adjusters familiar with Washington-specific road and weather conditions
- Member-owned mutual structure with a long-standing regional reputation
- Local customer service based in-state
PEMCO cons:
- Coverage doesn't travel if you move out of Washington or Oregon
- Smaller company footprint means fewer niche add-ons than the national carriers
Best for: Drivers planning to stay in Washington or Oregon for the foreseeable future. Verdict: Buy if you're not planning to relocate soon.
4. GEICO: best car insurance in Washington for digital-only shoppers
GEICO sells almost entirely through its app and website, with no local branch network to speak of in Washington. Quotes, policy changes, and ID cards all run through the same digital account.
GEICO pros:
- Fast online quotes without waiting for a callback
- Mobile app handles claims, ID cards, and payments
- Broad standard coverage menu at the basic and comprehensive levels
GEICO cons:
- No local agent to walk through coverage questions in person
- Customer service is phone and chat only, no storefront
Best for: Washington drivers who are comfortable managing a policy entirely on their phone. Verdict: Hold as one quote among several, not the only one you check.
5. Progressive: best car insurance in Washington for higher-risk drivers
Progressive built its name on the Name Your Price Tool and the Snapshot usage-based discount program, and it's historically more willing than most to write policies for drivers with a recent ticket or at-fault accident on record. That flexibility matters in a state where a single moving violation can spike a quote elsewhere.
Progressive pros:
- More flexible underwriting for drivers with a less-than-clean record
- Snapshot rewards safe driving habits with rate adjustments
- Broad coverage menu including rideshare endorsements
Progressive cons:
- Snapshot tracks driving behavior, which some drivers find intrusive
- Rates can move more than flat-rate competitors as driving data comes in
Best for: Washington drivers with a recent violation who got priced out somewhere else. Verdict: Buy specifically for higher-risk profiles.
6. Allstate: best car insurance in Washington for accident forgiveness
Allstate sells through both local agents and online direct channels in Washington, and it's best known for its accident forgiveness feature and the Drivewise telematics program. Accident forgiveness protects your rate after a single at-fault claim instead of letting it jump immediately.
Allstate pros:
- Accident forgiveness shields your rate after one at-fault claim
- Drivewise can lower premiums for consistently safe driving
- Local agents present in larger Washington cities
Allstate cons:
- Agent availability thins out in rural Washington counties
- Drivewise savings depend on actually using the app regularly
Best for: Drivers worried about one accident following them for years. Verdict: Hold — strong option, not the default for everyone.
How this ranking was built
Each company above is placed against the criteria listed earlier: local agent access, Washington-specific coverage fit, eligibility restrictions, digital tools, telematics programs, and multi-state licensing. No two carriers compete for the same "best for" slot, because the honest answer to "which is best" depends entirely on who's asking.
“The best car insurance company in Washington is the one that fits your driving record and your eligibility, not the one with the biggest ad budget.”
Which car insurance company should you choose in Washington in 2026?
For most Washington drivers without a military connection, State Farm's local agent network makes it the default starting point in 2026. If you or a family member served, USAA is worth checking first. Planning to stay in Washington or Oregon long-term makes PEMCO's regional focus worth a quote, and a recent ticket on your record means Progressive deserves a look before you assume every quote will be high.
None of this replaces getting real quotes side by side for your specific ZIP code and driving history. Coverage Lane connects Washington drivers with one licensed independent agent who checks multiple carriers directly, instead of fielding twelve separate sales calls.
Compare Washington auto quotes directly
One licensed independent agent checks multiple carriers for you, same business day.
FAQ
What is the minimum car insurance required in Washington in 2026?
Washington requires liability coverage of at least 25/50/10 in 2026 — $25,000 per injured person, $50,000 per accident, and $10,000 in property damage. Driving below these limits risks a suspended license.
Which car insurance company is best for Washington drivers overall?
State Farm is the strongest overall pick for most Washington drivers in 2026 because of its local agent network and bundling options. Military families and long-term Pacific Northwest residents may find USAA or PEMCO fit better.
Is USAA available to non-military drivers in Washington?
No, USAA membership is restricted to active-duty military, veterans, and their eligible family members. Washington drivers outside that group need to look at State Farm, PEMCO, GEICO, Progressive, or Allstate instead.
Does PEMCO only sell insurance in Washington?
PEMCO sells auto insurance only in Washington and Oregon. Moving out of the Pacific Northwest means you'll need to switch carriers.
Is Progressive good for drivers with a bad driving record in Washington?
Progressive is generally more flexible than most national carriers when underwriting drivers with a recent ticket or at-fault accident. Its Snapshot program can also lower rates for drivers who improve their habits over time.
Do I need underinsured motorist coverage in Washington?
Washington law requires insurers to offer underinsured motorist coverage on every policy, and you must reject it in writing if you don't want it. Most drivers keep it because the cost difference is small relative to the protection.
Should I bundle home and auto insurance in Washington?
Bundling auto with home or renters coverage through the same carrier often reduces the total cost versus separate policies. Whether it makes sense in 2026 depends on the specific carriers and your coverage needs on both policies.
One last thing
Washington law requires insurers to offer underinsured motorist coverage on every policy sold in the state, and the driver has to reject it in writing to skip it. A lot of Washington drivers don't realize they're carrying it, or don't realize they waived it, until they're filing a claim against someone with too little insurance of their own. Check your declarations page in 2026 before you assume either way.